SoLo Funds: Lend & Borrow

Screenshots
Details
- Rating
- 5.63K reviews
- Version
- 2.19.0
- Developer
- Solo Funds
Analysis by Norviv
When an unexpected bill lands between paydays, the usual choices are not especially appealing: ask someone you know, use a conventional credit product, or simply wait and hope the timing works out. SoLo Funds: Lend & Borrow takes a different approach by bringing borrowing and lending into one finance app. I found the idea immediately understandable, but the more important question is whether it remains useful after the first emergency has passed. In my experience, the answer depends heavily on whether you need occasional flexibility or are looking for a permanent replacement for a bank, credit card, or savings cushion.
The app is free and developed by Solo Funds. It is listed for Everyone, has passed the half-million-install mark, and carries an average rating of 4.6 from roughly twenty-five thousand ratings. Those figures suggest that the concept has reached a meaningful audience, but popularity alone does not make a borrowing tool suitable for every household. The real value is in how clearly you understand the arrangement before you request or provide money.
What feels useful during the first week
My first impression was that SoLo Funds is built around a very specific moment: you need a relatively small amount of help, you expect to repay it, and you would rather deal with people through a dedicated service than make an awkward personal request. That focus gives the app a more human feel than a standard loan form, while still keeping the interaction inside a structured financial product.
The borrowing side is the obvious starting point. Instead of treating the app like a general-purpose banking account, I would see it as a short-term option to investigate when an ordinary cash-flow problem appears. A utility payment, transport expense, or necessary household purchase can create a gap that does not justify a long application process. SoLo Funds is aimed at that gap, not at financing a large purchase or carrying a balance indefinitely.
The lending side is what makes the service different from a conventional cash-advance app. A person with spare funds can participate as a lender rather than simply leaving money unused. That creates a two-sided experience: borrowers are seeking timely support, while lenders are looking for the potential benefits of helping fund requests. I appreciate that the app does not present itself as only another emergency-borrowing shortcut.
Still, I would not install it expecting instant certainty. Financial apps often feel simple until identity checks, account connections, repayment timing, or a request’s availability become relevant. The sensible first-week routine is to create an account, read every screen that explains the transaction, and decide in advance how repayment would fit into your next income cycle. That preparation matters more here than the speed of opening the app.
A practical use case rather than a lifestyle app
Imagine that your phone bill and a necessary car repair arrive in the same week, while your next paycheck is several days away. I could see SoLo Funds being useful in that narrow situation if the amount requested is manageable and the repayment date does not collide with rent, food, or other fixed obligations. The app may provide a route to cover the immediate problem without turning it into a larger, open-ended debt.
Stories Picked for You

Life360 Works Better When Your Household Agrees on What to Share

YouVersion Bible Fits Scripture into Everyday Phone Routines

Matchington Mansion Review: Match-Three Puzzles With a Place to Restore

Android Auto Shows Why Safer Driving Software Does Less

Google Find Hub Runs on Shared Devices and Quiet Trust

Sygic GPS Navigation: The Ultimate Offline Travel Companion
My advice would be to calculate the full repayment impact before submitting anything. Do not ask for the maximum amount merely because it appears available. Start with the smallest sum that solves the actual problem, and leave enough room in your next budget for ordinary expenses. This is one of the app’s less obvious tests: the technology may make requesting money convenient, but convenience can hide how little flexibility remains afterward.
For lenders, the first week should be treated as an orientation period, not a hunt for effortless returns. Read how requests are presented, understand the timing involved, and consider whether the money can remain unavailable for a while. Lending is not the same as keeping cash in a traditional savings product. The potential benefit comes with uncertainty and a need to pay attention to the terms attached to each decision.
What separates it from familiar alternatives
A bank overdraft or credit card is usually more familiar and may be easier for someone who already has an established account and clearly understood terms. A paycheck-advance service may feel more automatic because it is tied to income information. Borrowing from a friend or relative can be cheaper or more flexible, but it also brings personal pressure. SoLo Funds sits between these choices: it gives the transaction a dedicated digital structure without making it identical to a bank loan.
That middle position is both its appeal and its limitation. If you need a predictable, reusable line of credit, a conventional product may be easier to plan around. If you only need an occasional bridge and want to avoid asking someone close to you, this app may feel more appropriate. I would not call it universally better; I would call it more specialized.
Whether it earns a place in a monthly routine
The strongest long-term use is not opening the app every day. It is knowing where it belongs in a personal financial plan. For a borrower, that means using it sparingly, only when the repayment path is realistic, and reviewing the upcoming budget before every request. For a lender, it means deciding whether checking opportunities fits comfortably into your broader financial habits.
That distinction is important because an emergency tool can become expensive or stressful when it turns into a recurring solution for an income shortfall. If I needed help every month to cover ordinary bills, I would treat that as a sign to review the budget, negotiate due dates, seek community assistance, or speak with a qualified financial counselor. Repeatedly borrowing to cover the same gap can make the app feel useful while leaving the underlying problem untouched.
SoLo Funds has more lasting value for people who experience occasional timing problems than for people whose regular expenses consistently exceed their income. Its role is closer to a financial pressure valve than a complete money-management system. That makes the app easier to judge honestly: it does not need to replace your bank to be useful, but it also should not be expected to repair an unstable budget.
How I would build a safer habit around it
I would keep a simple record of every request or lending decision, including the amount, expected date, and what the money is meant to cover. This is more useful than relying on memory, particularly when several automatic payments are scheduled close together. A note in a budgeting app or on paper can reveal whether the service is solving unusual problems or quietly becoming part of normal spending.
I would also separate the decision to borrow from the emotional urgency of the bill. Before opening the request screen, I would ask three questions: Is the expense essential? Will the next income payment cover repayment and basic needs? Is there a less costly option that does not create another obligation? That short pause is a practical safeguard, and it is especially valuable because mobile interfaces are designed to reduce friction.
Lenders need a different routine. I would never commit money that is needed for rent, food, debt payments, or an upcoming emergency. I would also avoid treating the lending feature like guaranteed income. The possibility of receiving benefits may be attractive, but the decision still involves tying up funds and accepting the possibility that the experience will require attention. A lender who wants total predictability may be better served by a conventional savings option.
Compatibility and setup expectations
The current version is 2.19.0, and the app supports Android 8.0 or later. That makes it accessible to many people using older Android phones, although compatibility is only one part of the setup experience. A finance app still requires patience with account details, verification steps, and the careful reading of transaction information. I would install it before an emergency rather than waiting until the exact moment a payment is due.
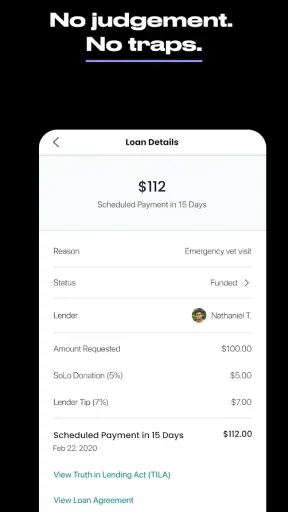
It is also worth remembering that being free to download does not mean that every financial action is costless or risk-free. The important question is the complete obligation connected with a specific transaction, not the price shown on the app store. I would review the relevant screens each time rather than assuming that a previous request tells me everything about a new one.
The Everyone age rating makes the app broadly accessible from a store-classification perspective, but financial responsibility is still an adult concern in practice. A younger user may be able to encounter the app, yet that does not remove the need for a clear repayment plan or responsible supervision where appropriate. I would not recommend any borrowing service simply because its content label sounds unrestricted.
Where the long-term experience can become tiring
The first source of fatigue is uncertainty. Borrowers may want a definite answer at a definite time, while lenders may want a clear expectation about when money will be returned. Any two-sided financial service has to balance those needs, and that can make the experience feel less predictable than using a bank account or an existing credit line.
The second is mental bookkeeping. A single short-term request may be easy to remember, but repeated transactions create dates and obligations that compete with ordinary bills. The app can organize the interaction, but it cannot make the repayment disappear. If you already feel overwhelmed by budgeting, adding another financial channel may increase stress rather than reduce it.
The third is temptation. Because the service is available through a phone, the distance between “I have a temporary problem” and “I will borrow again” is very small. I think the most responsible way to use it is to set a personal rule before an urgent situation occurs, such as only using it for essential expenses and never taking a new request to cover an earlier one.
Lenders can experience a different kind of fatigue: monitoring decisions, thinking about timing, and accepting that a potentially beneficial opportunity is not the same as guaranteed performance. If the process starts to feel like work or if the money is needed elsewhere, stepping back is the sensible choice. A finance app should serve your plan, not dictate it.
Who should probably choose another option
I would steer away from SoLo Funds if you need a large loan, long repayment horizon, or fully predictable revolving credit arrangement. It is also a poor fit if your income is so tight that repaying a short-term obligation would immediately force you to borrow again. In those cases, a bank, credit union, nonprofit assistance program, debt counselor, or carefully compared credit product may offer a more suitable path.
I would also be cautious if you dislike making decisions under uncertainty. The lending model may appeal to someone comfortable evaluating individual opportunities, but it is not the same as placing money in a simple account and forgetting about it. Likewise, a borrower who wants a completely automated experience may prefer an established financial provider with familiar account controls.
On the other hand, the app makes sense for a person who values a dedicated borrowing-and-lending marketplace, has a specific short-term need, and is willing to read the details rather than rush. It can also suit a lender who understands that participation requires judgment and that spare cash should genuinely be spare.
My lasting verdict after the novelty fades
SoLo Funds: Lend & Borrow earns a place on my shortlist of specialized finance apps, but not as a default replacement for a bank account or a complete budgeting system. Its lasting value comes from the narrow problem it addresses: connecting short-term borrowers with people willing to lend. That is a meaningful alternative to familiar options when the amount and timing are appropriate.
The app’s free entry point and clear two-sided concept make it easy to explore, while its 4.6 average and presence on more than half a million Android devices show that many users find the service worthwhile. I would still place more weight on personal affordability than on public popularity. A highly rated borrowing tool can remain the wrong choice if repayment would leave your household exposed.
For me, the best way to keep it useful is to treat it as an occasional backup, not a monthly allowance. Install it before you need it, understand the transaction flow, record every obligation, and borrow only what solves the immediate essential expense. Lenders should use equally strict discipline by committing only money they can leave unavailable and by viewing potential benefits as uncertain rather than promised.
The app earns lasting space when it supports a careful financial habit, not when it becomes the habit itself. If you can maintain that boundary, SoLo Funds offers a distinctive option that conventional banking does not quite replicate. If you cannot, the convenience that makes it attractive in the first week may become the very reason it creates fatigue over the following months.
Frequently Asked Questions
01What is SoLo Funds: Lend & Borrow, and how does it work?
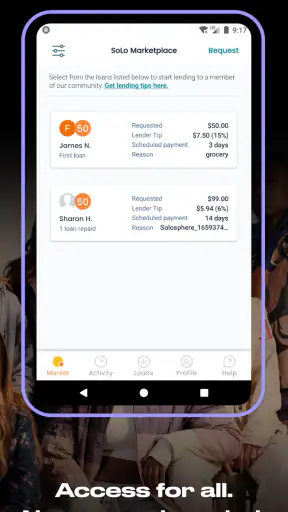
SoLo Funds is a community-based financial platform that allows eligible members to request small, short-term advances from other members. A borrower creates a request, explains the need, and chooses repayment terms, while lenders can review available requests and decide whether to contribute. The service is not a traditional bank loan, and availability, approval, and terms may vary by user and location.
02Is SoLo Funds safe and legitimate to use?
SoLo Funds uses account verification, transaction processing, and community-based features designed to help users lend and borrow through the app. However, no financial platform is completely risk-free. Borrowers should carefully review repayment obligations and fees, while lenders should understand that contributions may carry repayment risk. Always download the official app and read the current terms and privacy policy.
03How much money can I borrow through SoLo Funds?
The amount available through SoLo Funds depends on factors such as your account history, eligibility, location, repayment record, and the platform’s current policies. New users may have lower limits until they establish a track record. The app displays the amount and repayment details before you confirm a request, so review the total obligation carefully rather than assuming every user receives the same limit.
04Are there fees or additional costs for using SoLo Funds?
SoLo Funds may include optional or required costs depending on how you use the platform, such as service-related charges, expedited transfer fees, or other amounts shown during a transaction. Borrowers and lenders should inspect the final confirmation screen before accepting any request or transfer. Pricing and policies can change, so consult the in-app disclosures for the most accurate information.
05What happens if I cannot repay a SoLo Funds advance on time?
If you expect difficulty repaying an advance, contact SoLo Funds through the app as soon as possible and review the available support or repayment options. Late repayment may affect your account standing, borrowing access, or relationship with the lending community, and additional consequences may apply under the platform’s terms. Never request an advance unless you have a realistic plan to repay it.


